Published September 18, 2024
How the Federal Reserve’s Next Move Could Impact the Housing Market

Now that it’s September, all eyes are on the Federal Reserve (the Fed). The overwhelming expectation is that they’ll cut the Federal Funds Rate at their upcoming meeting, driven primarily by recent signs that inflation is cooling, and the job market is slowing down. Mark Zandi, Chief Economist at Moody’s Analytics, said:
“They’re ready to cut, just as long as we don’t get an inflation surprise between now and September, which we won’t.”
But what does this mean for the housing market, and more importantly, for you as a potential homebuyer or seller?
Why a Federal Funds Rate Cut Matters
The Federal Funds Rate is one of the key factors that influences mortgage rates – things like the economy, geopolitical uncertainty, and more also have an impact.
When the Fed cuts the Federal Funds Rate, it signals what’s happening in the broader economy, and mortgage rates tend to respond. While a single rate cut might not lead to a dramatic drop in mortgage rates, it could contribute to the gradual decline that’s already happening.
As Mike Fratantoni, Chief Economist at the Mortgage Bankers Association (MBA), points out:
“Once the Fed kicks off a rate-cutting cycle, we do expect that mortgage rates will move somewhat lower.”
And any upcoming Federal Funds Rate cut likely won’t be a one-time event. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:
“Generally, the rate-cutting cycle is not one-and-done. Six to eight rounds of rate cuts all through 2025 look likely.”
The Projected Impact on Mortgage Rates
Here’s what experts in the industry project for mortgage rates through 2025. One contributing factor to this ongoing gradual decline is the anticipated cuts from the Fed. The graph below shows the latest forecasts from Fannie Mae, MBA, NAR, and Wells Fargo (see graph below):
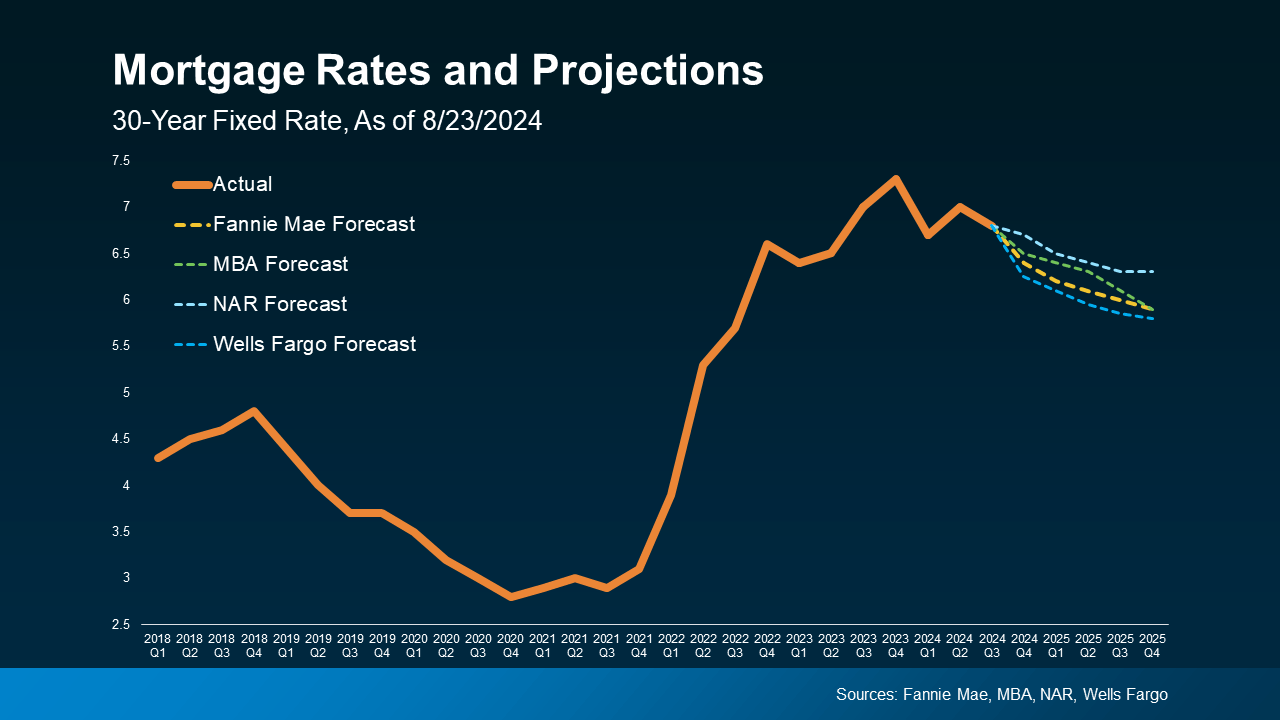 So, with recent improvements in inflation and signs of a cooling job market, a Federal Funds Rate cut is likely to lead to a moderate decline in mortgage rates (shown in the dotted lines). Here are two big reasons why that’s good news for both buyers and sellers:
1. It Helps Alleviate the Lock-In Effect
For current homeowners, lower mortgage rates could help ease the lock-in effect. That’s where people feel stuck within their current home because today’s rates are higher than what they locked in when they bought their current house.
If the fear of losing your low-rate mortgage and facing higher costs has kept you out of the market, a slight reduction in rates could make selling a bit more attractive again. However, this isn’t expected to bring a flood of sellers to the market, as many homeowners may still be cautious about giving up their existing mortgage rate.
2. It Should Boost Buyer Activity
For potential homebuyers, any drop in mortgage rates will provide a more inviting housing market. Lower mortgage rates can reduce the overall cost of homeownership, making it more feasible for you if you’ve been waiting to make a move.
What Should You Do?
While a Federal Funds Rate cut is not expected to lead to drastically lower mortgage rates, it will likely contribute to the gradual decrease that’s already happening.
And while the anticipated rate cut represents a positive shift for the future of the housing market, it’s important to consider your options right now. Jacob Channel, Senior Economist at LendingTree, sums it up well:
“Timing the market is basically impossible. If you’re always waiting for perfect market conditions, you’re going to be waiting forever. Buy now only if it’s a good idea for you.”
Bottom Line
The expected Federal Funds Rate cut, driven by improving inflation and slower job growth, is likely to have a positive, though gradual, impact on mortgage rates. That could help unlock opportunities for you. When you’re ready, let’s connect. That way you’ll be prepared to take action when the time is right for you.
With everyday expenses adding up and mortgage rates affecting monthly payments, it's understandable if you're wondering whether buying a home right now is the right move.
When the economy feels uncer...
After years of making a house your own, it can be hard to imagine living anywhere else. Maybe you've raised a family there, celebrated important milestones, or built lasting friendships with neighbors...
If you've been following mortgage rate headlines, you've probably seen the Federal Reserve mentioned more than once. And if you're thinking about buying or selling a home in Temecula, you may be wonde...
For many first-time buyers, owning a home can feel like a goal that's always a few years away. Saving for a down payment takes time, and with housing costs competing for space in your budget, it can b...
Higher mortgage rates don't just affect buyers. They can change what it takes to sell a home, too.
When borrowing costs rise, buyers tend to pay closer attention to their monthly payments. Even a rel...
If you’ve been following the headlines about mortgage rates, you may have seen reports that rates have climbed to their highest point since January 2025. For some buyers in Temecula, that news m...
Price cuts are becoming more common in today's housing market, and they can mean very different things depending on whether you're buying or selling a home in Murrieta.
For sellers, a price reduction...
If you’re planning to buy your next home in Murrieta, you’ve probably heard the old rule about saving 20% for your down payment.The truth is, you usually don’t have to. Plenty of loa...
Liz Jones
Realtor & Team Lead | Jones Realty Group | Keller Williams Realty
or another way